Take-home pay and tax by salary
This chart shows how an employee’s annual gross salary divides between estimated take-home pay and Income Tax plus employee National Insurance in 2026/27. It uses England, Wales and Northern Ireland rules.
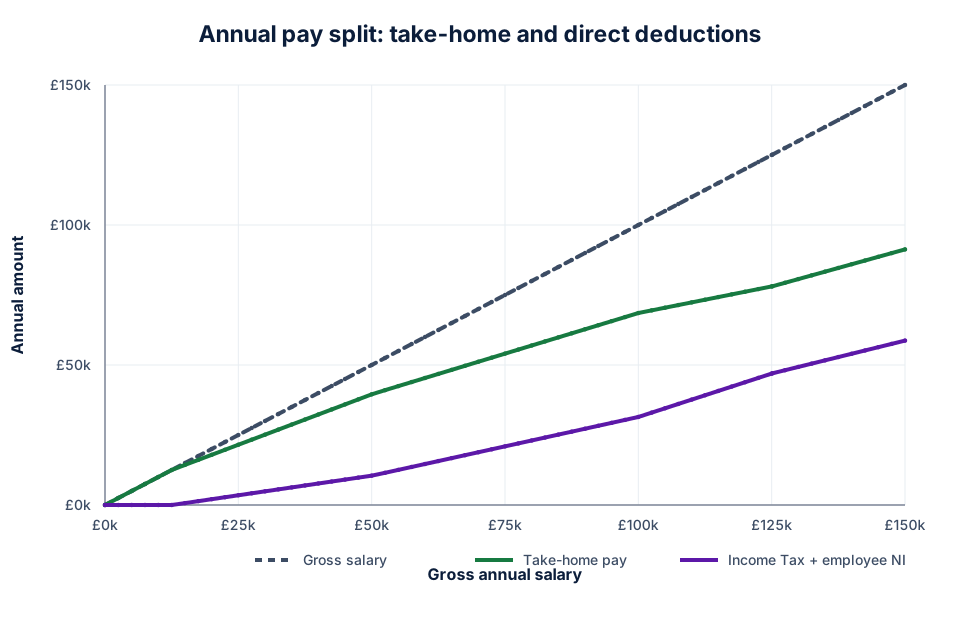
| Gross salary | Take-home | Income Tax + employee NI |
|---|---|---|
| £0 | £0.00 | £0.00 |
| £40,000 | £32,321.40 | £7,678.60 |
| £100,000 | £68,561.00 | £31,439.00 |
| £125,140 | £78,110.60 | £47,029.40 |
| £150,000 | £91,286.40 | £58,713.60 |
Embed this chart
Copy the HTML below. It loads one SVG image and links the chart back to its source page; it adds no script or tracking to your site.
<figure>
  <img src="https://moneyworkedout.co.uk/assets/charts/take-home-and-tax.svg" width="960" height="620" alt="Annual salary compared with take-home pay and Income Tax plus employee National Insurance, from zero to £150,000.">
  <figcaption>Chart by <a href="https://moneyworkedout.co.uk/charts/take-home-and-tax/">Money Worked Out</a>.</figcaption>
</figure>
Sources and chart notes
- Income Tax and PAYE bands: GOV.UK current Income Tax rates and Personal Allowances.
- Employee Class 1 NI: GOV.UK rates and thresholds for employers, 2026 to 2027.
- Take-home is calculated with the Money Worked Out tax engine. It assumes a standard code and excludes pension, student loan and benefits.
The SVG is a static image. It contains no script, tracker or external image request.